BLOG

Behind the numbers.

Code examples, market analysis, and data quality deep-dives.

Which Part of a 13F Is Worth Copying? Top Holdings Against New Buys in Python
How Much of a Ticker History Belongs to Another Company? Entity Resolution in Python
Which Corporate Line Item Turns First? Lead-Lag Analysis of S&P 500 Fundamentals in Python
Financial Data API Licensing: What You Can Redistribute
How to Pick a Benchmark for a Backtest
Are the Market’s Best Days Always Rebounds? Drawdown-State Analysis Across Sectors in Python
How Much of EPS Growth Comes From Share Buybacks? EPS Growth Decomposition in Python
How Long Does an S&P 500 Membership Last? Kaplan-Meier Survival Analysis in Python
How to Build a Stock Database in Python
Does Last Quarter’s Best Sector Stay on Top? Sector Rank Persistence in Python
How Much of the S&P 500’s Margin Expansion Is Index Turnover? Shift-Share Decomposition in Python
Trading Days vs Calendar Days: Why 252 Is Only an Average
How Much S&P 500 Profit Skips the Income Statement? Other Comprehensive Income in Python
How Many Calendar Anomalies Survive Multiple Testing? Bootstrap Reality Check in Python
How Long After Quarter End Do Financials Become Public? Filing Lag Analysis in Python
Does a Bollinger Band Squeeze Predict a Big Move? Band Width Analysis in Python
Do Sector Correlations Spike When the Market Falls? Conditional Beta Analysis in Python
Python Stock Data Libraries: What Each Gives You
Does the Balance Sheet Change Which Stocks Look Cheap? P/E Against EV/EBIT in Python
Can 2x Leveraged Sector ETFs Beat Their Sector? Volatility Drag Analysis in Python
Why Is Quarterly Cash Flow Year-to-Date in SEC Filings?
Are Earnings Harder to Forecast Than Revenue? Quarterly Time-Series Models in Python
Does Revenue Breadth Predict the Stock Market? A Quarterly Diffusion Index in Python
How Much Leverage Maximises Long-Run Growth? Kelly Sizing in Python
How to Run an Event Study in Python
Is a High-Margin Screen Just a Sector Bet? Sector-Neutral Profitability Ranking in Python
Does Proximity to the 52-Week High Beat Momentum? Conditional Quintile Sorts in Python
Does Negative Book Equity Signal Distress? S&P 500 Balance Sheet Screening in Python
How Late Does a Bear Market Signal Arrive? Turning-Point Detection in Python
How Much Historical Stock Data Do You Need?
Does Mean Reversion Survive Trading Costs? Moving-Average Deviations in Python
How Much Does Survivorship Bias Add to a Backtest? Point-in-Time S&P 500 Returns in Python
Does High Profitability Persist? Five-Year Transition Analysis in Python
Log Returns vs Simple Returns: Which to Use
Does Mean-Variance Optimisation Beat Equal Weighting? Out-of-Sample Test in Python
Which Sectors Actually Drive "Sell in May"? Sector Seasonality Analysis in Python
Does Free Cash Flow Coverage Predict Dividend Cuts Better Than the Payout Ratio? Point-in-Time Screening in Python
Bulk Stock Data Download vs API: Which to Use
Does a Stock's Beta Depend on the Benchmark? Cap-Weighted vs Equal-Weighted Markets in Python
How Long Does a Volatility Spike Take to Fade? Half-Life Estimation in Python
How Much Does a DCF Depend on Its Assumptions? Sensitivity Analysis in Python
How to Get a List of All US Stock Tickers
Do High-Idiosyncratic-Volatility Stocks Underperform? Residual Volatility Sorts in Python
Does Foreign Revenue Make a Stock Dollar-Sensitive? Firm-Level FX Beta in Python
Does Company Size Slow Revenue Growth? Gibrat's Law Test in Python
How to Get Stock Data Into Excel With Python
Does a Large Goodwill Balance Predict a Writedown? Impairment Risk Screening in Python
Does Revenue Concentration Explain Earnings Volatility? Segment Herfindahl Analysis in Python
Is Residual Momentum Better Than Raw Momentum? Market-Adjusted Decile Sorts in Python
Financial Data API Rate Limits: How Much Do You Need?
Does Index-Fund Ownership Make a Stock Move With the Market? 13F Ownership and Beta in Python
What Is Look-Ahead Bias in Backtesting?
How Much Drawdown Does Month-End Data Hide? Sampling Frequency and Maximum Drawdown in Python
Do Companies Pay the Tax They Report? Cash vs Book Tax Rates in Python
Does a High Dividend Payout Ratio Slow Earnings Growth? S&P 500 Cross-Section in Python
Web Scraping vs a Financial Data API: What Breaks
Did Earnings or the Multiple Drive the Last Decade of Returns? Return Decomposition in Python
What Does a Trailing Stop Cost? Stop-Loss Backtest in Python
Why Do Stock Prices Differ Between Data Sources?
Does an Inventory Build Predict a Margin Squeeze? Cross-Sectional Test in Python
How Much Revenue Does a Dollar of Acquisitions Buy? Growth Decomposition in Python
Do Companies Buy Back Stock at Good Prices? Dollar-Weighted Analysis in Python
What Data You Need for Comparable Company Analysis
How Much Does a Stock Fall on Its Ex-Dividend Date? Event Study in Python
How Seasonal Is Quarterly Revenue? Fiscal Quarter Share Analysis in Python
Do Reported Financials Follow Benford's Law? First-Digit Analysis in Python
What Is Book Value? Why Price-to-Book Stopped Working
How Far Apart Do S&P 500 Stocks Move? Cross-Sectional Return Dispersion in Python
Fama-French Factor Data: Download or Build Your Own?
How Much Does the Rebalance Date Change a Backtest? 21 Rebalance Days in Python
Does Trading Volume Predict Tomorrow's Volatility? Out-of-Sample Test in Python
Do Company Insiders Predict Their Own Stock's Returns? Form 4 Cross-Section in Python
How Many Independent Bets Are There in the S&P 500? Principal Component Analysis in Python
Can a Company's Revenue Be Forecast From Its Own History? Out-of-Sample Test in Python
What Is EBITDA and Why Do Sources Disagree?
Does the Turn-of-the-Month Effect Still Work? Calendar Anomaly Test in Python
Is the S&P 500 Getting More Capital Intensive? Capex Analysis in Python
Do High-Accrual Companies Underperform? Accruals Screening in Python
What Does a Financial Data API Cost?
Do Price Gaps Get Filled? Gap-Fill Rates Against a Random Walk in Python
What Expected Returns Does the S&P 500 Imply? Reverse Optimization in Python
Which Sectors Are Really Cyclical? Revenue Betas vs Stock Betas in Python
How to Build a Stock Dataset for Machine Learning
Comparing Companies With Different Fiscal Year Ends
How Much Has Corporate Debt Actually Repriced? Effective Interest Rates in Python
Does Deferred Revenue Predict Next Quarter's Sales? Leading Indicator Test in Python
How Much Debt Is Hidden in Operating Leases? Lease-Adjusted Leverage in Python
How Much Do Profits Move When Sales Move? Operating Leverage Regression in Python
How Concentrated Is the S&P 500? Index Weight Analysis in Python
How Long Is Cash Tied Up in a Business? Cash Conversion Cycle Analysis in Python
Broker API vs Data API for Historical Stock Data
Where to Get Free Cash Flow Data for Stocks in Python
Are Stock Returns Skewed? Return Skewness in Python
Do High-Margin Companies Trade at Higher Multiples? EV/Sales in Python
How Much Profit Becomes Cash? Free Cash Flow Conversion in Python
Which Sectors Lead Out of a Market Bottom? Sector Recovery Analysis in Python
Are Buybacks Funded by Cash Flow or by Debt? S&P 500 Payout Analysis in Python
What to Look for in Fundamentals Data
Does Cash on the Balance Sheet Cushion a Crash? Quintile Sorts in Python
Do Corporate Insiders Time the Market? S&P 500 Insider Buying Breadth in Python
Does Unstable Volatility Warn of Deeper Drawdowns? Vol-of-Vol Sorts in Python
Does Fast Asset Growth Predict Weak Stock Returns? Decile Sorts in Python
How to Replace yfinance in a Python Script
Does the Nasdaq-100 Index Effect Still Exist? Event Study in Python
Does the Piotroski F-Score Still Work? Quality Screening in Python
How Many S&P 500 Stocks Beat the Index? Return Breadth Analysis in Python
Why Beta Differs Between Data Sources
Where to Get Historical Dividend Data for Stocks
Does a High Dividend Yield Predict a Dividend Cut? Yield-Trap Screening in Python
Do Old Ticker Symbols Still Point to the Same Company? S&P 500 Ticker Recycling in Python
What Growth Is Priced Into the S&P 500? Reverse DCF in Python
Ticker vs CIK vs FIGI: Which Company ID to Use
Does Illiquidity Still Pay? Amihud Measure in the S&P 500 in Python
Where to Get R&D Spending Data for Public Companies
Does R&D Spending Predict Revenue Growth? Cross-Sectional Test in Python
What Actually Drives Return on Equity? DuPont Decomposition in Python
What Data Do You Need to Measure Portfolio Risk?
Does a 60/40 Portfolio Actually Cut Drawdowns? Stocks and Bonds in Python
Do Steady Margins Mean Calmer Stocks? Cross-Sectional Analysis in Python
Do Sectors Diversify When It Matters? Conditional Correlation in Python
How to Get Historical Market Cap Data in Python
How Much of the S&P 500 Survives 20 Years? Index Turnover Analysis in Python
Does Joining the S&P 500 Bring New Institutional Owners? 13F Event Study in Python
Is Volatility Seasonal? Calendar Month Analysis of Realized Volatility in Python
Does Fast Revenue Growth Force Companies to Borrow? Cash Funding Analysis in Python
How Far Back Does SEC EDGAR Data Go?
Are One-Time Charges Really One-Time? Charge Frequency Analysis in Python
Does Buying the Dip Work? Short-Term Reversal by Volatility Regime in Python
Alpha Vantage vs Massive vs xfinlink for Fundamentals
How Long Does a Stock Take to Recover From a 50% Fall? Drawdown Analysis in Python
Do Companies That Shrink Their Share Count Outperform? Net Buyback Yield in Python
How Much Does the Dow's Price Weighting Distort It? Index Weighting Analysis in Python
How to Get SEC Form 4 Insider Trading Data in Python
Can Anything Predict Next Month's Stock Returns? Out-of-Sample R-Squared Testing in Python
How Much of a Stock's Return Comes From Its Sector? Variance Decomposition in Python
Altman Z-Score: Where To Get It in Python
Do Value Screens Agree on Which Stocks Are Cheap? Multiple Overlap Analysis in Python
Annual vs Quarterly Financial Data: Which to Use
Do High Returns on Capital Persist? ROIC Fade Analysis in Python
Does Past Beta Predict Future Beta? Beta Stability Testing in Python
Do Defensive Sectors Actually Defend? Up and Down Capture in Python
How to Choose a Financial Data API
Do Small Caps Actually Beat Large Caps? Size Premium Test in Python
What If You Miss the Market's Best Days? Extreme-Day Analysis in Python
Does Rebalancing Add Return? Fixed-Weight vs Drift Portfolios in Python
Which S&P 500 Companies Are Closest to Default? Merton Distance-to-Default in Python
What Happens to Stocks Removed From the S&P 500? Replacement Pair Analysis in Python
Does the Golden Cross Work? 50/200 Moving Average Crossover Backtest in Python
Financial Data for Academic Finance Research
Does Skipping the Most Recent Month Improve Momentum? S&P 500 Decile Sorts in Python
Does Cointegration Survive Out of Sample? Pairs Trading Validation in Python
Which Dividends Are Not Covered by Cash? Free-Cash-Flow Coverage Screening in Python
GICS vs SIC vs NAICS: Which Industry Classification to Use
How Many Stocks Does It Take to Diversify? Random Portfolio Simulation in Python
How Many Days of Data Does a Volatility Estimate Need? Range-Based Estimators in Python
How Much of S&P 500 Cash Flow Is Stock Compensation? Cross-Sectional Analysis in Python
What Is a 13F Filing? Institutional Holdings Explained
Does Revenue Growth Explain Profit Growth? Cross-Sectional Decomposition in Python
How Much of the Nasdaq 100 Is Already in the S&P 500? Index Overlap Analysis in Python
How Often Does a 99% Value-at-Risk Limit Actually Break? VaR Backtesting in Python
Real-Time vs End-of-Day Market Data: Which Do You Need?
How Concentrated Are S&P 500 Earnings? Point-in-Time Index Analysis in Python
Does Volatility Scale With the Square Root of Time? Variance Ratio Test in Python
Does Goodwill Distort the Price-to-Book Screen? Goodwill-Adjusted Valuation in Python
How Are Shares Outstanding Reported (and Why They Disagree)
Do Low-Volatility Stocks Deliver Better Risk-Adjusted Returns? S&P 500 Quintile Sorts in Python
Does Trend Following Beat Buy and Hold? Time-Series Momentum in Python
Has the Stock-Bond Correlation Flipped? 60/40 Portfolio Risk in Python
What API to Use for a Stock Screener
Which Assets Hedge Inflation Shocks? Macro Factor Betas in Python
Does Covariance Shrinkage Beat the Sample Covariance? Minimum-Variance Portfolios in Python
Do Faster Inventory Turns Mean Thinner Margins? Gross Margin Return on Inventory in Python
SEC EDGAR API vs Fundamentals API: Which to Use
Does Fast Earnings Growth Persist? Rank Correlation Analysis in Python
Split Adjustment Explained: Adjusted Close vs Close
Which Trading Day of the Month Pays Best? Turn-of-the-Month Analysis in Python
Can You Use Yahoo Finance Data Commercially?
How Many Independent Bets Does a Nine-Sector Portfolio Give You? Eigenvalue Analysis in Python
Which Volatility Forecast Wins One Month Ahead? HAR vs EWMA in Python
How Concentrated Are Institutional Equity Portfolios? Form 13F Concentration Analysis in Python
Do Stocks Earn Their Returns Overnight or Intraday? Return Decomposition in Python
When Do Corporate Insiders Actually Trade? Form 4 Timing Analysis in Python
Data Requirements for Backtesting a Trading Strategy
What Is Survivorship Bias in Backtesting?
Do High Dividend Yields Come From Bigger Payouts or Falling Prices? Yield Decomposition in Python
Do Stocks Fall Harder Than They Rise? Downside Beta vs Upside Beta in Python
Does Volatility Targeting Improve Sharpe Ratios? Seven-Asset Backtest in Python
Free Stock Market Data APIs: What You Actually Get
How to Give an LLM Financial Data With an MCP Server
Does Post-Earnings Announcement Drift Survive Real Filing Dates? PEAD Event Study in Python
Do Insider Buying Clusters Predict Returns? Signal Testing in Python
Does the S&P 500 Index Effect Still Exist? Event Study in Python
Are Companies Leaving the S&P 500 Faster Than They Used To? Index Survival Analysis in Python
Does Gross Profitability Predict Stock Returns? Quintile Factor Test in Python
What Growth Rate Is the Market Pricing In? Reverse DCF in Python
Does a Strong Balance Sheet Cushion Drawdowns? Leverage and Downside Risk in Python
Does Ticker Recycling Corrupt a Mean-Reversion Backtest? Entity-Resolved Z-Scores in Python
How Much of a Growth Screen's Backtested Edge Is Survivorship Bias? Point-in-Time Index Testing in Python
Why Do Leveraged ETFs Decay? Measuring Volatility Drag in Python
Are Consumer Staples Margins Shrinking Under Inflation? Gross Margin Trend Analysis in Python
Do Weak Jobs Reports Predict Market Drawdowns? NFP Surprise Event Study in Python
Is the Rotation From Tech to Industrials Backed by Earnings? Relative EPS Growth Analysis in Python
Is the Semiconductor Rally Broadening Beyond NVIDIA? Return Dispersion Analysis in Python
Which Stocks Benefit Most When Oil Prices Fall? Oil Beta Screening in Python
Do Bond Returns Predict Stock Returns? Granger Causality Test in Python
Which Stocks Actually Drive Portfolio Returns? Shapley Value Attribution in Python
Does "Sell in May" Still Work? Calendar Anomaly Backtest in Python
How to Build Complete Price History Through Ticker Changes? Entity Resolution in Python
Are KO and PEP Cointegrated? Pairs Trading Signal Construction in Python
Which Commodities Have the Strongest Momentum? Rotation Backtest in Python
Which Commodity ETFs Have the Worst Tail Risk? Expected Shortfall in Python
Are Gold Miners Leveraged Gold Bets? Rolling Beta Analysis in Python
Does the Base-Metals-to-Gold Ratio Lead Cyclical Stocks? Signal Test in Python
Can Risk Parity Tame Commodity Volatility? Portfolio Optimization in Python
Are Power Stocks Becoming an AI Infrastructure Trade? Momentum Screening in Python
Which AI Chip Stocks Have Margin Momentum? Profitability Trend Analysis in Python
Which AI Stocks Are Cheapest Relative to Growth? Growth-Adjusted Valuation in Python
Does AI Stock Leadership Persist? Momentum Backtest in Python
Which AI Stocks Have the Cleanest Balance Sheets? Net Cash Screening in Python
Can Risk Parity Reduce Mega-Cap Drawdowns? Portfolio Optimization in Python
Which Growth Stocks Are Self-Funding? Cash-Flow Quality Screening in Python
Which Sectors Struggle When the Dollar Rallies? Sector Rotation Analysis in Python
Do Cheap Stocks Hold Up When Bonds Sell Off? Valuation Rotation in Python
Does the Nasdaq 100 Have Better Growth Quality Than the Dow? Index Constituent Analysis in Python
Do Healthcare Cash-Flow Margins Predict Returns? Signal Evaluation in Python
Which Dividend Stocks Survive a Cash-Flow Stress Test? Dividend Screening in Python
Does Heavy Insider Selling Predict Weak Returns? Insider Flow Test in Python
Can Quality Screens Reduce Small-Cap Balance-Sheet Risk? Russell 2000 Test in Python
Which Retailers Have Positive Operating Leverage? Margin Screening in Python
Is MSTR a Leveraged Bitcoin Proxy? Rolling Beta Analysis in Python
Is Micron's Memory Cycle Recovering? Inventory and Margin Forecasting in Python
Which Sectors Work When Bonds Rally? Rate-Sensitive Rotation in Python
Do One-Month Price Extremes Reverse? Signal Evaluation in Python
Do Low-Volatility S&P 500 Stocks Reduce Drawdowns? Factor Test in Python
Is AI Capex Paying Back Fast Enough? Revenue Hurdle Forecasting in Python
Could Shorter AI Asset Lives Hit Earnings? Depreciation Stress Test in Python
How Much AI Capex Risk Can a Portfolio Remove? Constrained Optimization in Python
Is the AI Capex Trade Crowded? Rolling Volatility and Sector Rotation in Python
Did the AI Boom Come From Existing S&P 500 Members? Point-in-Time Momentum Test in Python
Is AI Revenue Circular? Customer-Vendor Capex Loop Analysis in Python
Is the AI Trade Connected to Private Credit? Rolling Correlation Network in Python
Is Apollo More Balance-Sheet Sensitive Than Peers? Leverage Screen in Python
Are AI Earnings Supported by Cash Flow? Accrual and Capex Screen in Python
Can Defensive Stocks Hedge AI Drawdowns? Basket Regime Test in Python
How Fast Does the Market Price In Fed Decisions? FOMC Event Study in Python
How Much Are Options Sellers Overpaid? The Variance Risk Premium in Python
Which Companies Have the Worst Earnings Quality? Sloan Accrual Screen with Geographic Revenue Data in Python
Does the Oil-to-Gold Ratio Signal Recessions? XLE/GLD Backtest in Python
Is AI Spending Crowding Out Free Cash Flow? Capex Sustainability Across the Mag 7 in Python
Does a Long Energy / Short Bonds Portfolio Capture Inflation Surprises? Factor Construction in Python
Can a Hidden Markov Model Detect Oil Market Regimes? HMM Analysis in Python
Do Grain Prices Predict Food Inflation? Granger Causality Test in Python
Does the Corporate Credit Spread Predict Stock Market Crashes? BAA-AAA Spread Analysis in Python
Do Oil Stocks Hedge Inflation? Rolling Beta Analysis in Python
Which Stocks Are Most Rate-Sensitive? Equity Duration via Bond Beta in Python
Which Companies Have the Highest Accrual Ratios? Earnings Quality Screening in Python
Is Alpha Persistent or Decaying? Rolling Sharpe Ratio Analysis in Python
Are Markets Trending or Mean-Reverting? Hurst Exponent Analysis in Python
Is Consumer Discretionary vs Staples a Leading Indicator? XLY/XLP Ratio Analysis in Python
Does Heavy Capex Predict Future Stock Returns? Capital Expenditure Analysis in Python
How to Estimate Cost of Equity Using CAPM in Python
Is Volatility Predictable? Testing for Volatility Clustering in Python
Which Industrials Are Overleveraged? Net Debt to EBITDA Screening in Python
GM Before and After Bankruptcy: Why Entity Resolution Matters for Financial Data
What Is Adjusted Beta? Merrill Lynch Beta Shrinkage in Python
How Good Is a Stock Pick? Information Ratio and Tracking Error in Python
Do Stock Returns Follow a Normal Distribution? Testing for Fat Tails in Python
Which Large Caps Have the Highest Free Cash Flow Yield? FCF Screening in Python
Which Sectors Won Over 5 Years? Sector Rotation Analysis in Python
How to Forecast Stock Volatility with GARCH Models in Python
Are Stock Prices Mean-Reverting? Augmented Dickey-Fuller Test in Python
How to Calculate CAPM Alpha and Beta with Regression in Python
How to Compare Sector Sharpe Ratios and Sortino Ratios in Python
DELL: Why Stitching Historical Price Data Together Is Wrong
How to Analyze Drawdown and Recovery for Bank Stocks in Python
How to Screen SaaS Stocks by Revenue Growth and Cash Flow in Python
How to Screen REITs by Dividend Yield and Valuation in Python
How Correlated Are the Magnificent 7? Intra-Group Correlation in Python
AAPL vs XOM: Do Individual Stocks Have Seasonal Patterns?
How to Rank Large-Cap Stocks by Momentum in Python
How to Build a Multi-Endpoint Financial Dashboard in Python
How to Compare Volatility Across Energy Stocks in Python
How to Screen Healthcare Stocks by Valuation in Python
How to Build a Sector Correlation Matrix for Portfolio Diversification in Python
How to Find Oversold and Overbought Stocks Using Z-Scores in Python
How to Measure Earnings Quality: Cash Flow vs Net Income in Python
How to Build a Multi-Factor Stock Screen in Python (Value + Momentum + Quality)
How to Build a Simple DCF Model for Any Stock in Python
How to Screen Tech Stocks by Revenue Growth in Python
How to Screen Stocks by Balance Sheet Health in Python
Is "Sell in May" Real? SPY Monthly Seasonality Over 10 Years
How to Compare Sector Performance YTD Using Python
How to Screen Dividend Stocks by Yield and Quality in Python
How to Calculate Max Drawdown and Recovery Time for Any Stock in Python
How to Compare Profitability Across Mega-Cap Tech Stocks in Python
Why Ticker Symbols Are Unreliable: The Recycling Problem Every Quant Should Know
How to Calculate and Compare Stock Volatility in Python
How to Screen Blue-Chip Stocks by P/E Ratio in Python
How to Track Companies Through Ticker Changes, Bankruptcies, and Renames in Python
S&P 500 Turnover: How Much the Index Has Changed Since 2010
How to Calculate Stock Beta and Correlation in Python
← All articles

Which Corporate Line Item Turns First? Lead-Lag Analysis of S&P 500 Fundamentals in Python

What’s the question?

Every quarter, several hundred large companies report what they sold, what it cost to produce, what sits in the warehouse, what customers still owe, and what was spent on plant and equipment. That is the raw material the official macro series are built from, at company grain.

A great deal of commentary treats the inventory cycle as a leading indicator, on the reasoning that companies build stock ahead of demand and run it down ahead of a slowdown. If that is right, aggregate inventory growth is an early-warning gauge. If inventory moves after revenue instead, it confirms something already visible, and it arrives with a filing delay on top. The cross-correlation function settles the matter: it correlates two series across a range of time shifts and reports where the correlation is strongest. A peak at a positive shift means the line item moved first.

The approach

  1. Pull quarterly figures for the current S&P 500 roster on revenue, cost of sales, selling and administrative expense, inventory, receivables, payables, and capital spending.
  2. Companies close their books on their own calendars, so assign each report to the calendar quarter whose end date it sits closest to, one report per company per quarter.
  3. Hold the sample constant: only companies with an unbroken record on all seven items across the 66 quarters from 2010Q1 to 2026Q2 stay in. Requiring inventory and cost of sales keeps firms that make and move physical goods, and leaves out banks and insurers, which report neither line.
  4. Convert each company’s series to growth against the same quarter a year earlier, then take the cross-sectional median. A dollar sum tracks the largest two or three companies rather than the typical one, and the mean of a growth ratio blows up when a denominator lands near zero.
  5. Correlate each line item against revenue at shifts of minus four to plus four quarters, then repeat with 2020Q1 through 2021Q4 removed, since a shock that large can set the answer by itself.

Code

import numpy as np
import pandas as pd
import xfinlink as xfl

xfl.set_api_key("YOUR_API_KEY")  # free at https://xfinlink.com/signup

SERIES = ["revenue", "cost_of_sales", "selling_general_admin", "inventory",
          "accounts_receivable", "accounts_payable", "capital_expenditures"]
FIELDS = ["revenue", "cost_of_revenue", "cost_of_goods_sold", "selling_general_admin",
          "inventory", "accounts_receivable", "accounts_payable", "capital_expenditures"]
QS = pd.period_range("2010Q1", "2026Q2", freq="Q")

tickers = sorted(xfl.index("sp500")["ticker"].dropna().unique())
raw = pd.concat([xfl.fundamentals(tickers[i:i + 100], start="2008-06-01",
                                  end="2026-09-17", period_type="quarterly",
                                  fields=FIELDS, max_rows=200000)
                 for i in range(0, len(tickers), 100)], ignore_index=True)

raw["quarter"] = (raw["period_end"] + pd.Timedelta(days=45)).dt.to_period("Q") - 1
raw["cost_of_sales"] = raw["cost_of_revenue"].fillna(raw["cost_of_goods_sold"])
raw = (raw.sort_values(["ticker", "quarter", "period_end"])
          .drop_duplicates(["ticker", "quarter"], keep="last"))

names = sorted(raw["ticker"].dropna().unique())
wide = {f: raw.pivot_table(index="ticker", columns="quarter", values=f)
             .reindex(index=names, columns=QS) for f in SERIES}
keep = np.logical_and.reduce([wide[f].notna().all(axis=1).values for f in SERIES])
panel = pd.Index(names)[keep]

med = pd.DataFrame({f: (wide[f].loc[panel].pct_change(4, axis=1) * 100).median(axis=0)
                    for f in SERIES}).dropna()

rev = med["revenue"]
profile = pd.DataFrame({f: {L: med[f].shift(L).corr(rev) for L in range(-4, 5)}
                        for f in SERIES if f != "revenue"}).T
print(profile.round(2))

Full script with formatting and visualisation: corporate-line-item-lead-lag-sp500-python.py

Output
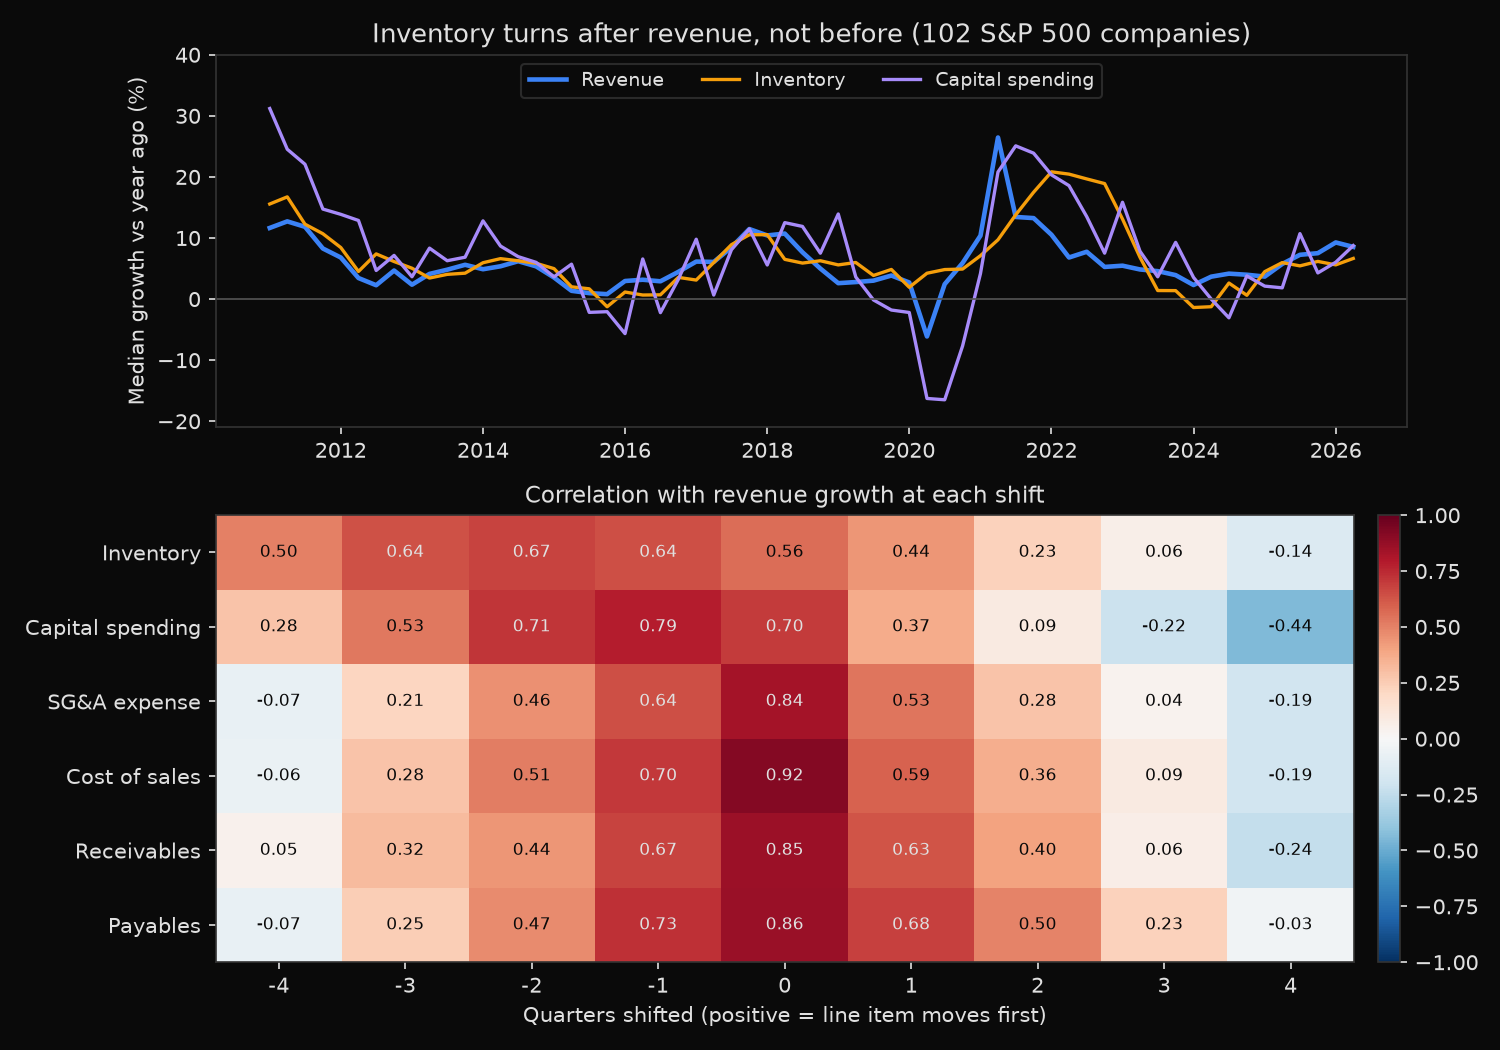
Median year-on-year growth in revenue, inventory and capital spending for 102 S&P 500 companies since 2011, above a table of the correlation between each line item and revenue growth at shifts of minus four to plus four quarters
Panel: 102 companies, unbroken quarterly records 2010Q1 to 2026Q2
Sectors: Health Care 26, Industrials 23, Information Technology 21,
         Consumer Discretionary 12, Consumer Staples 11, Materials 8, Real Estate 1
Growth series: 62 quarters, 2011Q1 to 2026Q2

Positive lag = turns before revenue. Negative lag = turns after revenue.
       Line item  Peak lag  Corr at peak  Corr same qtr  Peak ex-2020/21  Latest YoY %
       Inventory        -2         0.674          0.560                0           6.7
Capital spending        -1         0.786          0.697                0           8.8
    SG&A expense         0         0.835          0.835                0           8.4
   Cost of sales         0         0.919          0.919                0           7.3
     Receivables         0         0.854          0.854                0           8.6
        Payables         0         0.863          0.863                0           9.9

Cross-correlation against revenue growth, by lag in quarters:
                         -4    -3    -2    -1     0     1     2     3     4
cost_of_sales         -0.06  0.28  0.51  0.70  0.92  0.59  0.36  0.09 -0.19
selling_general_admin -0.07  0.21  0.46  0.64  0.84  0.53  0.28  0.04 -0.19
inventory              0.50  0.64  0.67  0.64  0.56  0.44  0.23  0.06 -0.14
accounts_receivable    0.05  0.32  0.44  0.67  0.85  0.63  0.40  0.06 -0.24
accounts_payable      -0.07  0.25  0.47  0.73  0.86  0.68  0.50  0.23 -0.03
capital_expenditures   0.28  0.53  0.71  0.79  0.70  0.37  0.09 -0.22 -0.44

Same profile excluding 2020Q1-2021Q4:
                         -4    -3    -2    -1     0     1     2     3     4
cost_of_sales         -0.22  0.11  0.49  0.71  0.86  0.64  0.36 -0.00 -0.28
selling_general_admin -0.10  0.06  0.29  0.53  0.78  0.68  0.52  0.28  0.03
inventory             -0.00  0.23  0.42  0.58  0.66  0.51  0.31  0.05 -0.19
accounts_receivable   -0.21  0.03  0.32  0.60  0.86  0.83  0.61  0.34  0.05
accounts_payable      -0.33 -0.05  0.27  0.58  0.82  0.72  0.55  0.31  0.04
capital_expenditures   0.18  0.42  0.59  0.68  0.69  0.42  0.25 -0.04 -0.24

Turning points (median year-on-year growth):
  Revenue           cycle peak 2021Q2 at  26.5%   trough 2024Q1 at   2.3%
  Inventory         cycle peak 2022Q1 at  20.8%   trough 2024Q1 at  -1.4%
  Capital spending  cycle peak 2021Q3 at  25.1%   trough 2024Q3 at  -3.1%

Latest quarter 2026Q2: Revenue +8.5%, Cost of sales +7.3%, SG&A expense +8.4%,
Inventory +6.7%, Receivables +8.6%, Payables +9.9%, Capital spending +8.8%

What this tells us

Not one of the six line items has its peak correlation at a positive shift. Nothing in this panel leads revenue, in the full sample or with the pandemic years removed.

Four of the six peak in the same quarter as revenue. Cost of sales at 0.92 is close to an accounting identity, and receivables at 0.85 and payables at 0.86 are tied to the quarter’s billing; those four lines restate revenue in different units and carry no timing information. Inventory and capital spending do separate themselves, in the wrong direction for a forecaster: inventory peaks two quarters after revenue at 0.674 against 0.560 in the same quarter, and capital spending peaks one quarter after at 0.786.

The 2021 and 2022 episode shows the mechanism at unmissable scale. Median revenue growth topped out at 26.5% in 2021Q2 and had fallen to 6.8% by 2022Q2, while inventory growth did not peak until 2022Q1, at 20.8%, and was still running at 18.9% in 2022Q4 against revenue growth of 5.3%. Goods ordered during the boom kept arriving into a slowdown that had already started, and the overhang shows up as a lag.

The lag is not symmetric. Both series troughed together in 2024Q1, revenue at 2.3% and inventory at minus 1.4%, because a buffer is filled deliberately and drained involuntarily. Removing 2020 and 2021 moves every peak to zero, inventory included, where the profile reads 0.66 contemporaneously against 0.58 one quarter later. The measured length of the lag depends on the pandemic shock; the sign does not, since no peak moves to a positive shift in either sample.

So what?

Aggregate inventory growth should not be used as a recession signal. By the time it turns, revenue has been turning for two or three quarters and the filings reporting it are another six weeks old. The series is good for sizing a correction already under way: the gap between revenue growth and inventory growth measures how much stock has still to be worked off, and in 2022Q4 that gap stood at 13.6 percentage points.

The forecastable direction runs the other way. Revenue growth predicts inventory and capital spending one to two quarters ahead, which is usable for anyone modelling supplier volumes, freight demand, or capital goods orders. Revenue growth has climbed from 2.3% at the 2024Q1 trough to 8.5% in 2026Q2, with inventory at 6.7%, so the lag structure implies another quarter or two of catching up before the two meet.

For a nowcast built on filings, treat the income statement and the balance sheet as a confirmation layer with unusual breadth, not as an early signal. Anything that genuinely leads has to come from outside those lines: orders, bookings, deferred revenue, prices. Before trusting a claim that a fundamental series leads the cycle, run the nine-column correlation on it. The answer costs one line of code and is frequently the opposite of the claim.

Built with xfinlink — free financial data API for Python. pip install -U xfinlink
← All articles